Why Restaurants and Food Service Businesses Need Workers’ Comp
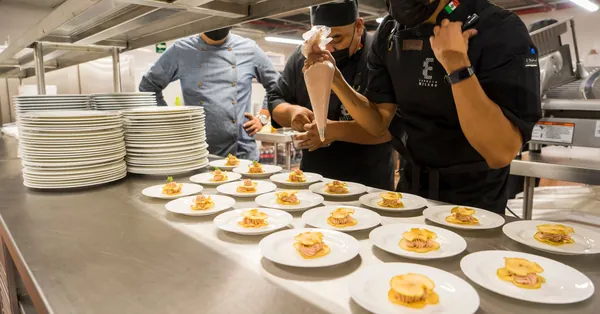
Restaurants and food service operations face a unique set of risks. From kitchen burns to slip-and-fall injuries, these businesses are high-risk environments for work-related injuries. As an agency, you're responsible for ensuring these businesses comply with workers’ comp requirements and get the right coverage for their employees. This is especially important in states where workers’ comp is mandatory for businesses with employees, regardless of size. The key to accurate quoting is understanding the right class code and coverage needs for the specific type of restaurant or food service business.
NCCI Class Codes for Restaurants and Food Service
When quoting workers’ comp for restaurants, the correct class code is essential for accurate rating and policy terms. Below are the relevant NCCI class codes commonly used for this industry:
- 9082: Restaurant NOC
- 9083: Restaurant: Fast Food – replaced by a state-specific code in several states.
- 9079: Restaurant NOC
- 9078: Commissary Work
- 9061: Club—NOC & Clerical – with state-specific codes in DE and PA.
Note that NCCI codes vary by state, and some states like California, Delaware, Pennsylvania, and Michigan use their own code sets. Always confirm the correct class code for the location of the business.
Key Considerations for Quoting Restaurant Workers’ Comp
When quoting workers’ comp for a restaurant or food service business, consider the following:
- Employee Exposure – Full-service restaurants often have more employees than fast-food chains and may include cooks, servers, and dishwashers. Each role carries different risks.
- Exposure Basis – The class code determines the exposure basis, so report payroll the way the classification needs it.
- Owner Inclusion – Whether an owner who works in the restaurant is covered automatically or must elect in depends on the state and how the business is set up.
- Hours of Operation – 24-hour restaurants may have higher risks due to night shifts and increased foot traffic.
Workers’ Comp vs. General Liability in the Food Service Industry
It's important to distinguish between workers’ comp and general liability insurance. Workers’ comp covers injuries to employees while they're on the job, such as burns from hot food or slips in the kitchen. General liability insurance, on the other hand, protects the business from claims made by third parties, such as a customer who slips and falls in the restaurant. While both are important, they serve different purposes. Ensure the business has both types of coverage to be fully protected.
For more information on general liability insurance for food service businesses, visit our general liability coverage page.
How to Get a Quote for Restaurant Workers’ Comp
At Cennairus, we make it simple to submit a workers’ comp quote for a restaurant or food service business. Here's how it works:
- Enter the business information, including the type of restaurant and the number of employees.
- Select the appropriate NCCI class code based on the type of food service provided.
- Input payroll details, hours of operation, and any special equipment used.
- Review the quote for accuracy and coverage needs.
Cennairus sends your submission to several carriers and specialty markets; some are connected by API and others are worked by email or a program desk. Each carrier answers with a price, a referral to its underwriter, or a decline. For more details about how our platform works, visit our home page.
Best Practices for Managing Restaurant Workers’ Comp
Managing workers’ comp for restaurant clients requires attention to detail and ongoing communication. Here are some best practices:
- Review Class Code Changes – As the business grows or changes operations, the appropriate class code may shift. Regularly review the coverage to ensure it aligns with the current business model.
- Monitor Claims – Restaurants can be high-claims industries. Keep an eye on claim history to help carriers assess risk and avoid premium spikes.
- Stay Updated on State Requirements – Workers’ comp laws vary by state. Ensure your clients are in compliance with their local requirements, especially in states like Ohio, North Dakota, Washington, and Wyoming where coverage is handled through state funds.
- Build Relationships with Carriers – Understand the appetite of carriers for restaurant risks. This helps you position the business in the best light and secure favorable terms.
Specialty Workers’ Comp Programs for Restaurants
Some restaurants may fit specialty workers’ comp programs. These programs are often designed for businesses with unique risks or operations. At Cennairus, we have access to purpose-built programs and PEO partner referrals for risks that fit them. These programs can be particularly useful for small restaurants or those with high-risk operations.
Next Steps for Your Agency
Quoting workers’ comp for restaurants and food service businesses requires a solid understanding of class codes, risk exposure, and coverage requirements. By following best practices and leveraging the right tools, you can help your clients secure the coverage they need at the best possible price. For more insights on class codes and niche industries, explore our class codes and niches category. And if you're ready to start submitting quotes, join Cennairus and reach several carriers and specialty markets with one submission.