The Real Value of Automation for Restaurants and Food Service
Restaurants and food service businesses face a complex insurance landscape. Between workers' comp, general liability, liquor liability, and property coverages, agencies often deal with high-volume submissions and tight turnaround times. Automation can cut through the noise in specific, practical ways — not just for underwriters, but for agencies placing these accounts.
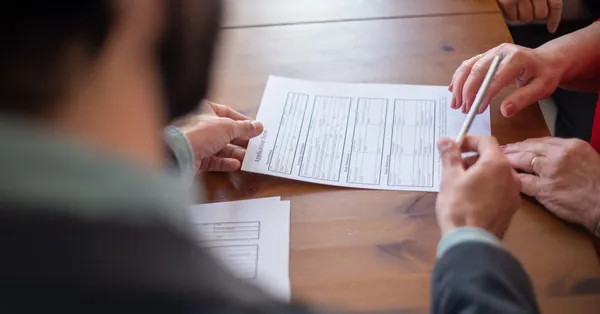
For example, food service workers’ comp claims can vary drastically between states. New York's NYCIRB has its own classification system, and California uses the WCIRB's. Manually parsing this information across dozens of submissions is time-consuming. When a platform can read and structure ACORD forms and loss runs automatically, it reduces back-and-forth and speeds up the placement process.
Key Use Cases Where Automation Adds Value
- Keeping state codes straight: The same restaurant can carry a different code number from one state to the next — NCCI's fast-food code 9083 is 9079 in California — and structured data makes the difference visible. The producer still confirms the code. Getting this right matters for accurate premium calculation and compliance.
- Document handling: Restaurants often submit a mix of forms — liquor licenses, health department certifications, and employee rosters. An automated system can extract relevant data from these documents, reducing the need for manual data entry and minimizing errors.
- Policy servicing: Once a policy is placed, restaurants often need frequent updates — new locations, changes in hours, or staff additions. Keeping the policies and their documents in one platform makes those changes easier to manage.
Common Misconceptions About Automation in Food Service
Automation is not a replacement for underwriter judgment, especially in high-risk accounts. A food truck business in a state with high workers' comp rates may still need manual underwriting to assess risk accurately. Automation shines in the repetitive, high-volume tasks — not in nuanced decision-making.
Another misconception is that automation eliminates the need for agency expertise. Restaurants in high-traffic areas may face different risk profiles than those in low-traffic locations, and an agency must know how to position that in a submission. Automation supports the process, it does not replace the agency's role in understanding the business and its risk.
How Agencies Can Leverage Automation Tools
Agencies can use automation to streamline their workflow in several ways. One submission that reaches multiple carriers through an AI-native platform like Cennairus can save time and reduce the need for repeated data entry. Keeping the policies in one place makes it easier to manage a portfolio of restaurant accounts and respond to client requests quickly.
Where a tool offers reporting, agencies can track placement rates, premium changes, and loss trends for their food service clients. This makes it easier to identify patterns — like a spike in claims during certain seasons — and adjust their approach accordingly.
What Agencies Should Look for in Automation Tools
Not all automation tools are built the same. When evaluating an insurtech platform, agencies should look for a few key features:
- Carrier integration: The platform should connect with a network of top-rated carriers across lines like workers' comp, general liability, and liquor liability. This ensures that a single submission can be reviewed by multiple underwriters.
- Document parsing: The system should be able to read and extract information from ACORD forms, loss runs, and other common insurance documents. This reduces the need for manual data entry and minimizes errors.
- Real-time updates: The platform should allow agencies to update policies in real time — for example, when a restaurant adds a new location or expands its hours. This ensures that the policy remains accurate and up to date.
- Reporting and analytics: The tool should provide insights into placement rates, premium changes, and loss trends for food service accounts. This helps agencies identify patterns and adjust their approach as needed.