Start with the basics: What do they haul, and where?
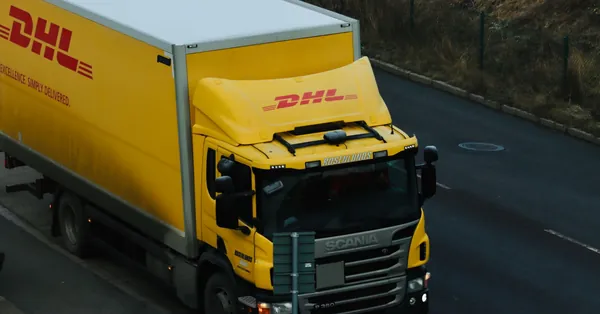
The first step in writing a trucking or transportation account is to understand the business model. Ask the client what type of cargo they haul — dry, refrigerated, hazardous, or oversized — and whether the loads are regional, local, or cross-country. This helps determine the appropriate commercial auto class code and whether specialized endorsements or coverage might be needed. A mismatch here can lead to coverage gaps or unnecessary carrier scrutiny later. For example, a refrigerated truck hauling food in California would require different considerations than a flatbed hauling construction materials in Texas.
How many trucks and drivers are involved?
Ask for the exact number of vehicles and the status of each driver. Are they employees, owner-operators, or a mix? This distinction affects whether the carrier will require proof of workers' compensation coverage for each driver. If the client uses owner-operators, clarify if they're contracted for specific loads or on a regular basis. This can influence carrier appetite and the need for additional documentation.
What’s the driving pattern and mileage?
Ask about the typical daily mileage and driving hours. If the operation involves long-haul or overnight driving, this increases the risk profile. It also affects whether the account might require a higher-risk classification or if a specialized program would be a better fit. Some carriers are more flexible with mileage than others, so knowing this upfront can guide your submission strategy. Be sure to ask if the drivers operate within a defined geographic area or across state lines, as cross-border operations may involve more documentation and compliance checks.
Are they a for-hire or private carrier?
Clarify whether the client is a for-hire carrier (hauling for third parties) or a private carrier (moving goods for their own business). This distinction impacts the type of coverage and regulations the account falls under. If the client is for-hire, ask for its USDOT number and its FMCSA compliance history. This is also a key factor in determining which carriers will accept the risk, as appetite for for-hire operations can vary widely.
What’s the claims history and loss control?
Ask for the client's recent claims history, including the number of claims, their nature (e.g., collision, cargo, or bodily injury), and any ongoing investigations. Also, ask about their loss control measures — do they have a driver training program, safety incentives, or telematics in place? Carriers look for this information to assess the client's risk management approach, which directly affects underwriting decisions and pricing. A poor loss history or lack of proactive safety measures can lead to higher premiums or rejection, particularly from carriers with conservative underwriting teams.
Do they need cargo or liability coverage beyond the vehicle?
Ask if the client needs coverage for cargo, trailers, or non-owned vehicles. These are common in transportation accounts and can add layers to the submission. If the client operates in states with independent rating systems like California or New York, be prepared to clarify the local workers' comp class codes. Make sure the client understands that different lines (e.g., general liability, cargo, or hired and non-owned auto) may be structured separately. For instance, cargo is a separate coverage from commercial auto liability.
What’s their experience and financial stability?
Ask about the client’s experience in the industry and their financial stability. Carriers are more likely to accept a risk from an established, well-capitalized operator. If the business is new or has a short operating history, ask for details about the owner’s background and how they obtained their fleet. This can help you determine whether the client is a better fit for a carrier with a more flexible appetite or a program designed for emerging businesses. Financial strength is often a key factor in placement, especially in competitive markets.
What exclusions or conditions do they understand?
Ask the client if they understand the typical exclusions in commercial auto coverage, such as off-road use, unauthorized drivers, or damage to cargo. Clarifying expectations early can prevent misunderstandings later. If the client is unclear, explain in plain terms what their policy would and would not cover. This is especially important for owner-operators or small fleets that may not be familiar with the nuances of commercial auto insurance. Make sure they know what to expect before finalizing the submission.
How do they want to be quoted — by class code or exposure?
Ask if the client prefers a quote based on a standard class code or if they want the submission tailored to their specific exposure. Hauling is not one classification: local hauling, long-distance hauling and parcel or courier delivery are rated separately, and the number each one carries depends on the state. Make sure you're clear on whether the client is asking for a standard rate or a custom submission. In non-NCCI states, like California or New York, class codes vary by rating bureau, so a one-size-fits-all approach won’t work. Be prepared to adjust your submission strategy based on the client’s specific needs and the carrier’s requirements.